GoAffPro Pricing Explained
GoAffPro pricing: Hobby Free, Premium $49, Business from $99. No sales %, vs UpPromote.
Awin alternatives after ShareASale closed Oct 6, 2025—pick CJ, Impact, PartnerStack, or feat. by seat, not logo. 9,500+ advertisers stayed on Awin.

TL;DR: Awin alternatives are a seat choice, not a logo swap. ShareASale closed into Awin on October 6, 2025 (9,500+ advertisers / 250,000 publishers). Pick CJ for classic retail scale, Impact for partnership-cloud ops ($30/$500/$2,500 + 2.5%), PartnerStack for B2B SaaS ecosystems (Network 43% vs 3%), or feat. when named sellers need a co-branded storefront.
Most “Awin alternatives” posts still behave like 2024. They rank logos. Some still treat ShareASale as a live twin. That research is already wrong. Awin finished the ShareASale upgrade and closed the old platform on October 6, 2025, consolidating more than 9,500 advertisers and 250,000 active publishers onto one seat (Awin).
If you are hunting awin alternatives, you are usually trying to finish one of four jobs: stay in a classic publisher marketplace, run a partnership cloud, build a B2B SaaS partner ecosystem, or give named people a co-branded place to sell. Best affiliate marketing network already ranked network shapes. CJ vs Awin already owns the automation wiring fork. This page owns the alternatives shortlist after consolidation—by seat, not by headcount vanity.
Key takeaways:
Awin alternatives are the platforms merchants and publishers evaluate when Awin’s classic-network seat is the wrong hire—or when they want a second seat beside it—matched to a specific partnership job rather than a bigger logo list.
They are not “anything with affiliates.” A classic network (Awin, CJ) sells discovery across many programs and program-by-program approval. A partnership cloud (Impact) sells contracts, multi-partner types, and ops tooling with a published SaaS ladder. A B2B PRM (PartnerStack) sells SaaS partner ecosystems and marketplace gating. A co-branded storefront marketplace (feat.) sells an approve-then-page fork for an existing offer. Calling all four “networks” is how teams waste a quarter.
The vernacular matches the fork. Shopify clothing merchants have described ShareASale/Awin inventory as “huge coupon and marketing companies,” not creators (r/ecommerce). Ops threads after the ShareASale shutdown call Impact “powerful but definitely not plug-and-play” (r/AffiliateOps). Those are fit comments. They are not a price census.
This page does not replace Impact vs feat or PartnerStack vs feat. Those spokes own pairwise forks. This spoke owns the alternatives shortlist for people who typed “Awin alternatives” after the consolidation.
Picking the wrong seat costs months of approvals, tracking rebuilds, and publisher re-education. The consolidation made stale roundups expensive. PMA put 2024 U.S. affiliate spend at $13.62B, generating $113B in e-commerce sales (PMA). That money still runs through classic networks, clouds, PRMs, and storefronts. The meter is the job, not the logo.
Why the seat decision is the expensive part:
Awin alternatives work as an Alternative Seat Ladder: decide the job first, then hire Classic network (CJ), Partnership cloud (Impact), B2B SaaS PRM (PartnerStack), or Co-branded storefront (feat.). Stay on Awin when classic discovery still fits. Add a second seat when the job changes—do not migrate for logo fashion.
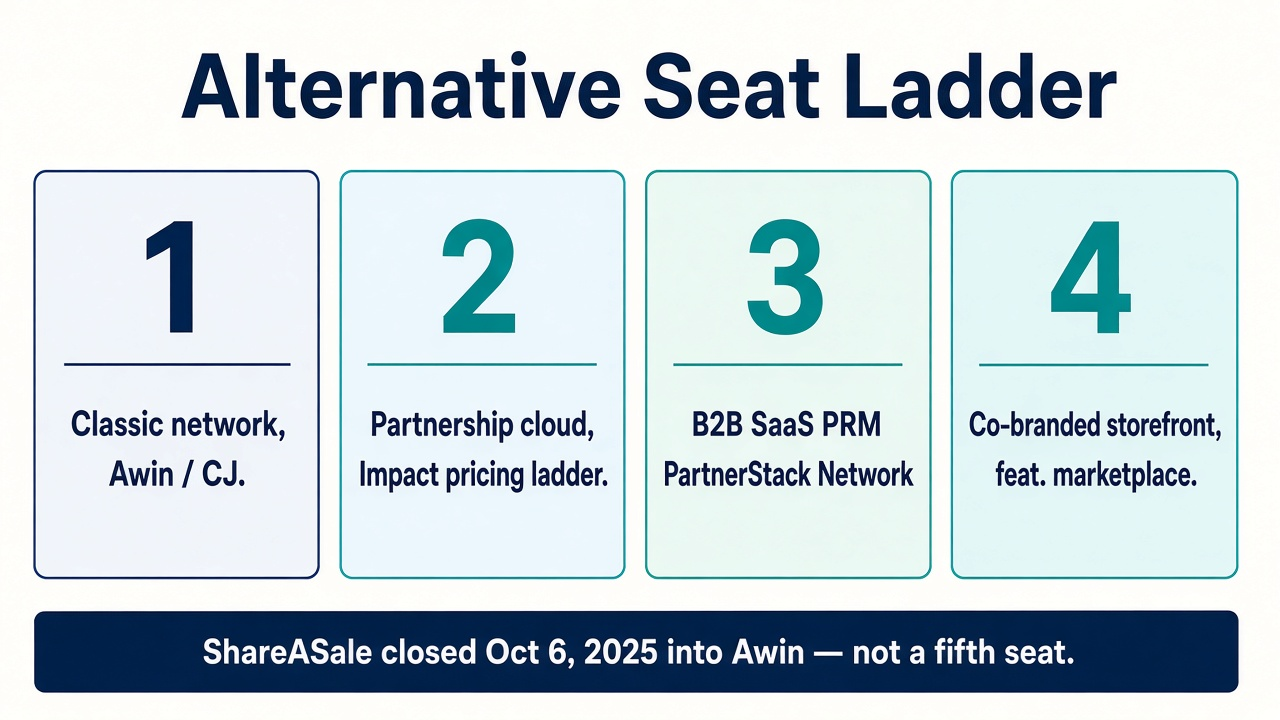
Source: Editorial job-fit framework from Awin consolidation facts, Impact published pricing, PartnerStack Network chart, and feat. approve-then-storefront mechanics. Taxonomy diagram; no invented feat. fees.
Classic networks win when you need a large publisher marketplace and program-by-program applications. Awin’s consolidation story is the freshness fact for 2025–2026: 9,500+ advertisers, 250,000 publishers, ShareASale closed October 6, 2025 (Awin).
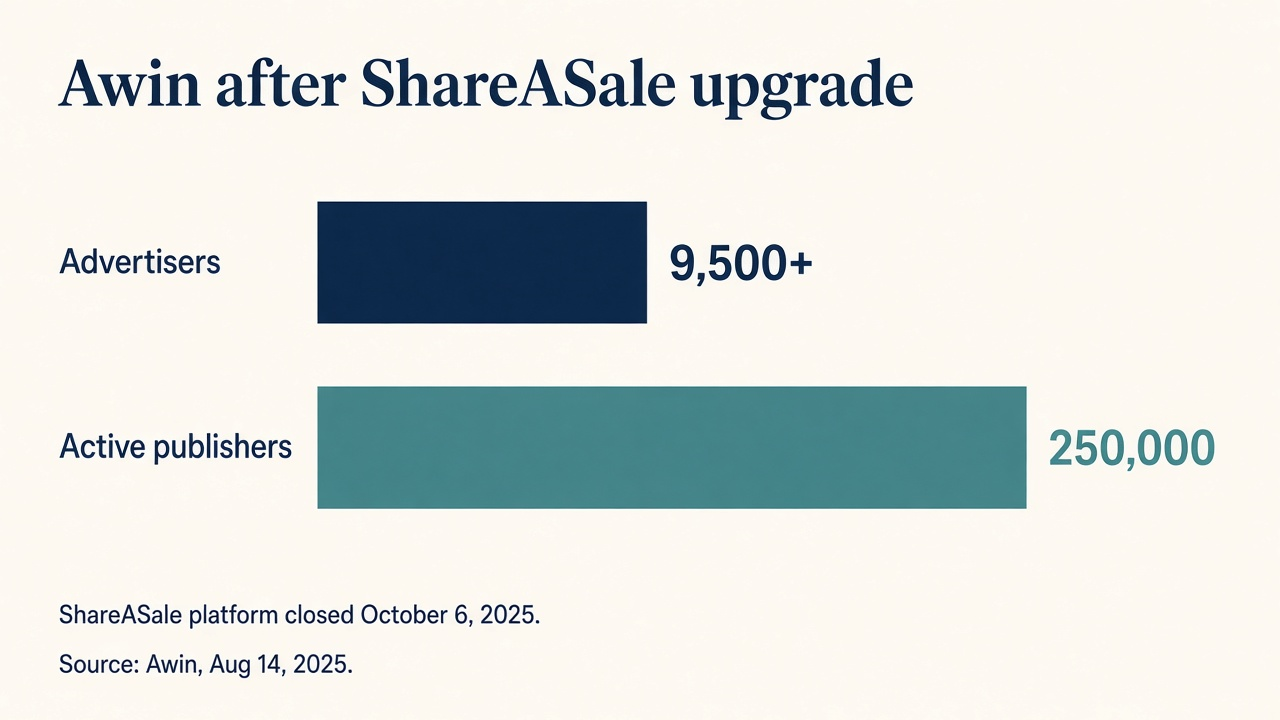
Source: Awin, Aug 14, 2025 ShareASale upgrade announcement. https://www.awin.com/us/news-and-events/awin-news/awin-shareasale-new-era
CJ remains the familiar giant for established retail and content publishers. CJ’s homepage publishes vendor scale markers—1B+ monthly reach, 14B+ annual interactions, 157M annual transactions, $16B+ annual revenue—label those as CJ marketing claims, not a third-party audit (CJ). If your question is API wiring (GraphQL commissions, S2S posts, webhooks), stop here and read CJ vs Awin. That spoke owns automation. This spoke only needs the seat: classic marketplace depth.
Impact wins when you need partner types, contracts, multi-domain programs, and risk tooling—not only a bigger coupon catalog. Public pricing lists Starter from $30/month, Essentials from $500, Pro from $2,500, Enterprise by quote, plus 2.5% on partner-driven transactions (Impact). Essentials is the first rung that names 90,000 partners in the Partner Marketplace. Setup fee exists and is unpublished as a single dollar—there is no public dataset for that invoice; confirm on the quote.
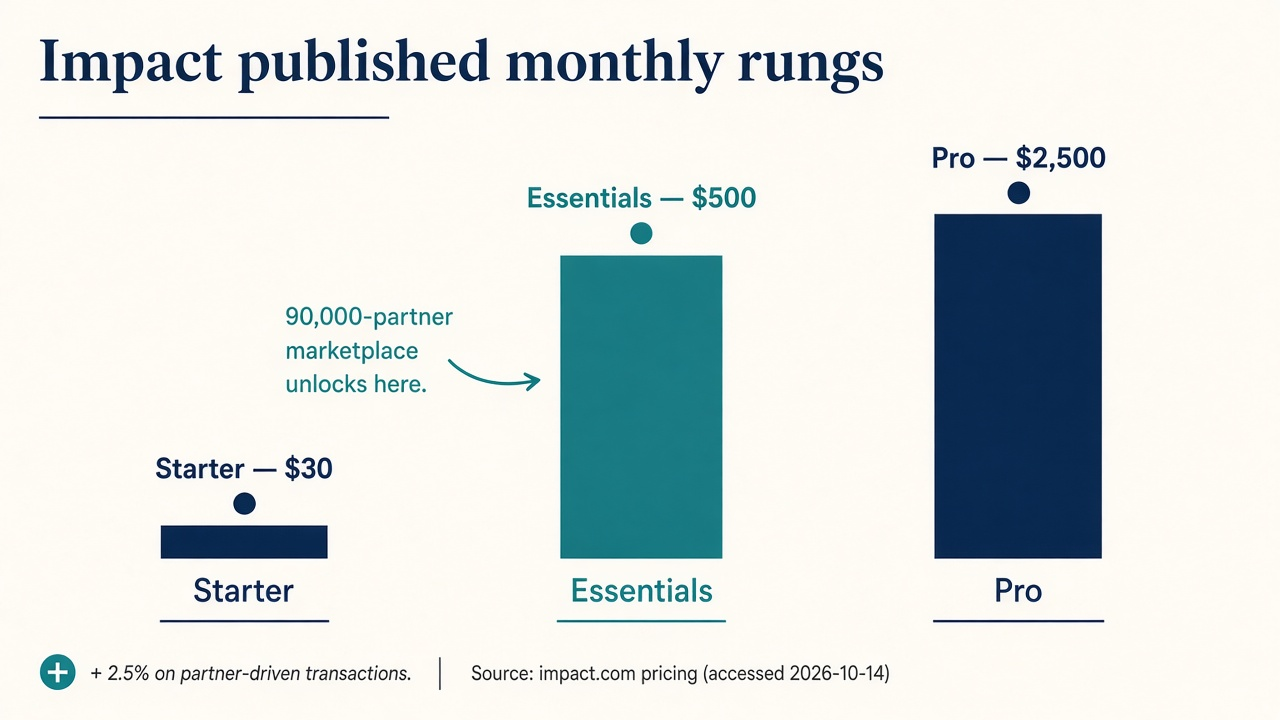
Source: Impact.com integrated platform prices, accessed 2026-10-14. https://impact.com/integrated-platform-prices/
Shopify’s volume heuristic and Reddit’s “not plug-and-play” comments point the same way: Impact is the ops upgrade when Awin’s marketplace shape is no longer the bottleneck (Shopify; r/AffiliateOps). For cloud versus storefront detail, use Impact vs feat.
PartnerStack wins when the inventory is software partners—affiliates, agencies, referrals, co-sell—not physical retail coupon sites. Public pricing is Launch / Growth / Enterprise with dollars confirmed in a demo (PartnerStack pricing). The public proof that matters for alternatives research is Network quality: 43% of Network-approved partners earn a commission versus 3% outside (PartnerStack).
Do not buy PartnerStack because a listicle put it next to Awin. Buy it when B2B partner motions are the job. Pairwise detail lives on PartnerStack vs feat and PartnerStack vs Impact for B2B affiliates.
feat. wins when you can name the sellers and each one should share a co-branded storefront of your existing offer—with a revenue split on every sale. That is a different first screen from a tracking link into your PDP. Affiliate software vs storefront already named the gap across trackers and clouds. feat. does not recruit a 250,000-publisher marketplace for you. Marketplace listing is optional. Live percentages appear in-product. Never invent a feat. platform cut to “beat” Impact’s 2.5%.
| Seat | Example | Published proof you can cite | First screen after approval | Wrong buy if… |
|---|---|---|---|---|
| Classic network | Awin (post-SaS), CJ | Awin 9,500+ / 250,000; CJ vendor 1B+ reach claims | Program links + network UI | You needed named creators with a sell page |
| Partnership cloud | Impact | $30 / $500 / $2,500 + 2.5%; 90,000 marketplace at Essentials | Contracts, codes, cloud dashboard | You only needed ten Stripe referral links |
| B2B SaaS PRM | PartnerStack | Network 43% vs 3%; quote-only dollars | Partner ecosystem / marketplace | Your SKU is DTC apparel coupon inventory |
| Co-branded storefront | feat. | In-product fees only (no invented public cut) | Forked storefront on locked offer | You needed enterprise fraud scoring or SaS-scale discovery |
Sources: Awin; CJ; Impact; PartnerStack Network chart.
Q: What are the best Awin alternatives in 2026? A: Match the seat. CJ for classic retail/publisher scale. Impact for partnership-cloud ops with published $30/$500/$2,500 rungs plus 2.5% on partner-driven sales. PartnerStack for B2B SaaS ecosystems (Network 43% vs 3%). feat. when named sellers need a co-branded storefront. ShareASale is not on the list.
Q: Is ShareASale still a ShareASale competitor or Awin alternative? A: No. Awin completed the ShareASale upgrade (9,500+ advertisers / 250,000 publishers) and closed the ShareASale platform on October 6, 2025. Compare Awin as the live classic-network seat, then evaluate true alternatives by job.
Q: Should I leave Awin for Impact? A: Leave only when the job outgrew classic marketplace shape—multi-partner contracts, deeper attribution/risk tooling, or marketplace discovery at Essentials ($500+) and above. Impact is powerful and not plug-and-play; confirm the setup fee on a quote because there is no public single-dollar dataset for it.
Q: How much do Awin alternatives cost? A: Impact publishes Starter from $30/month, Essentials $500, Pro $2,500, plus 2.5% on partner-driven transactions. PartnerStack and many classic-network advertiser seats are quote-led. feat. shows live percentages in-product. There is no honest universal “average alternative monthly fee.”
Q: Do I need an Awin alternative if I only want creators to sell my product? A: Often you need a different seat, not a twin network. If the failure mode is coupon-heavy inventory and thin creator fit, a co-branded storefront path (feat.) or a tighter partner filter (PartnerStack for SaaS; Impact marketplace for broader partner types) beats another logo with the same classic-network shape.
Awin alternatives are an Alternative Seat Ladder problem. ShareASale already closed into Awin’s 9,500+ / 250,000 footprint on October 6, 2025. CJ keeps the classic scale conversation honest. Impact publishes the cloud sticker. PartnerStack proves B2B Network quality at 43% vs 3%. feat. is the storefront seat when people you can name should sell. Pick the seat that finishes the job—then list the offer on feat. if that job is co-branded selling.
GoAffPro pricing: Hobby Free, Premium $49, Business from $99. No sales %, vs UpPromote.
Refersion pricing: Launch $39+3%, Growth $199+2%. Affiliate-sales fees, crossover math, vs UpPromote.
UpPromote pricing: Free, Growth $29.99+2%, Pro $89.99+1.5%. Performance fees, crossover math, vs ReferralCandy.